# Making strategies (/platform/quant/strategies)
Ask Quant, our coding agent, for a strategy in the chat. The difference from an indicator is the script itself: a strategy is Pine Script® with a `strategy(...)` declaration instead of `indicator(...)`, which means it can place simulated entries and exits and produce a backtest. Quant plots it on the [active chart](/platform/charts/introduction#the-active-cell) in Vela, our next-generation charting platform, like any other script.
Backtesting is research, not prophecy: it tells you, with data, how an idea behaved on the history you ran it on. It doesn't predict how it will behave next.
You can create, edit, and remove multiple indicators and strategies in the same chat; name the strategy you want to change when working with several. Scripts stay on the workspace until removed. See [Several scripts in one chat](/platform/quant/indicators#several-scripts-in-one-chat) and [Keep it on the workspace](/platform/quant/indicators#keep-it-on-the-workspace) for **My Scripts** and the current **Add to chart** behavior.
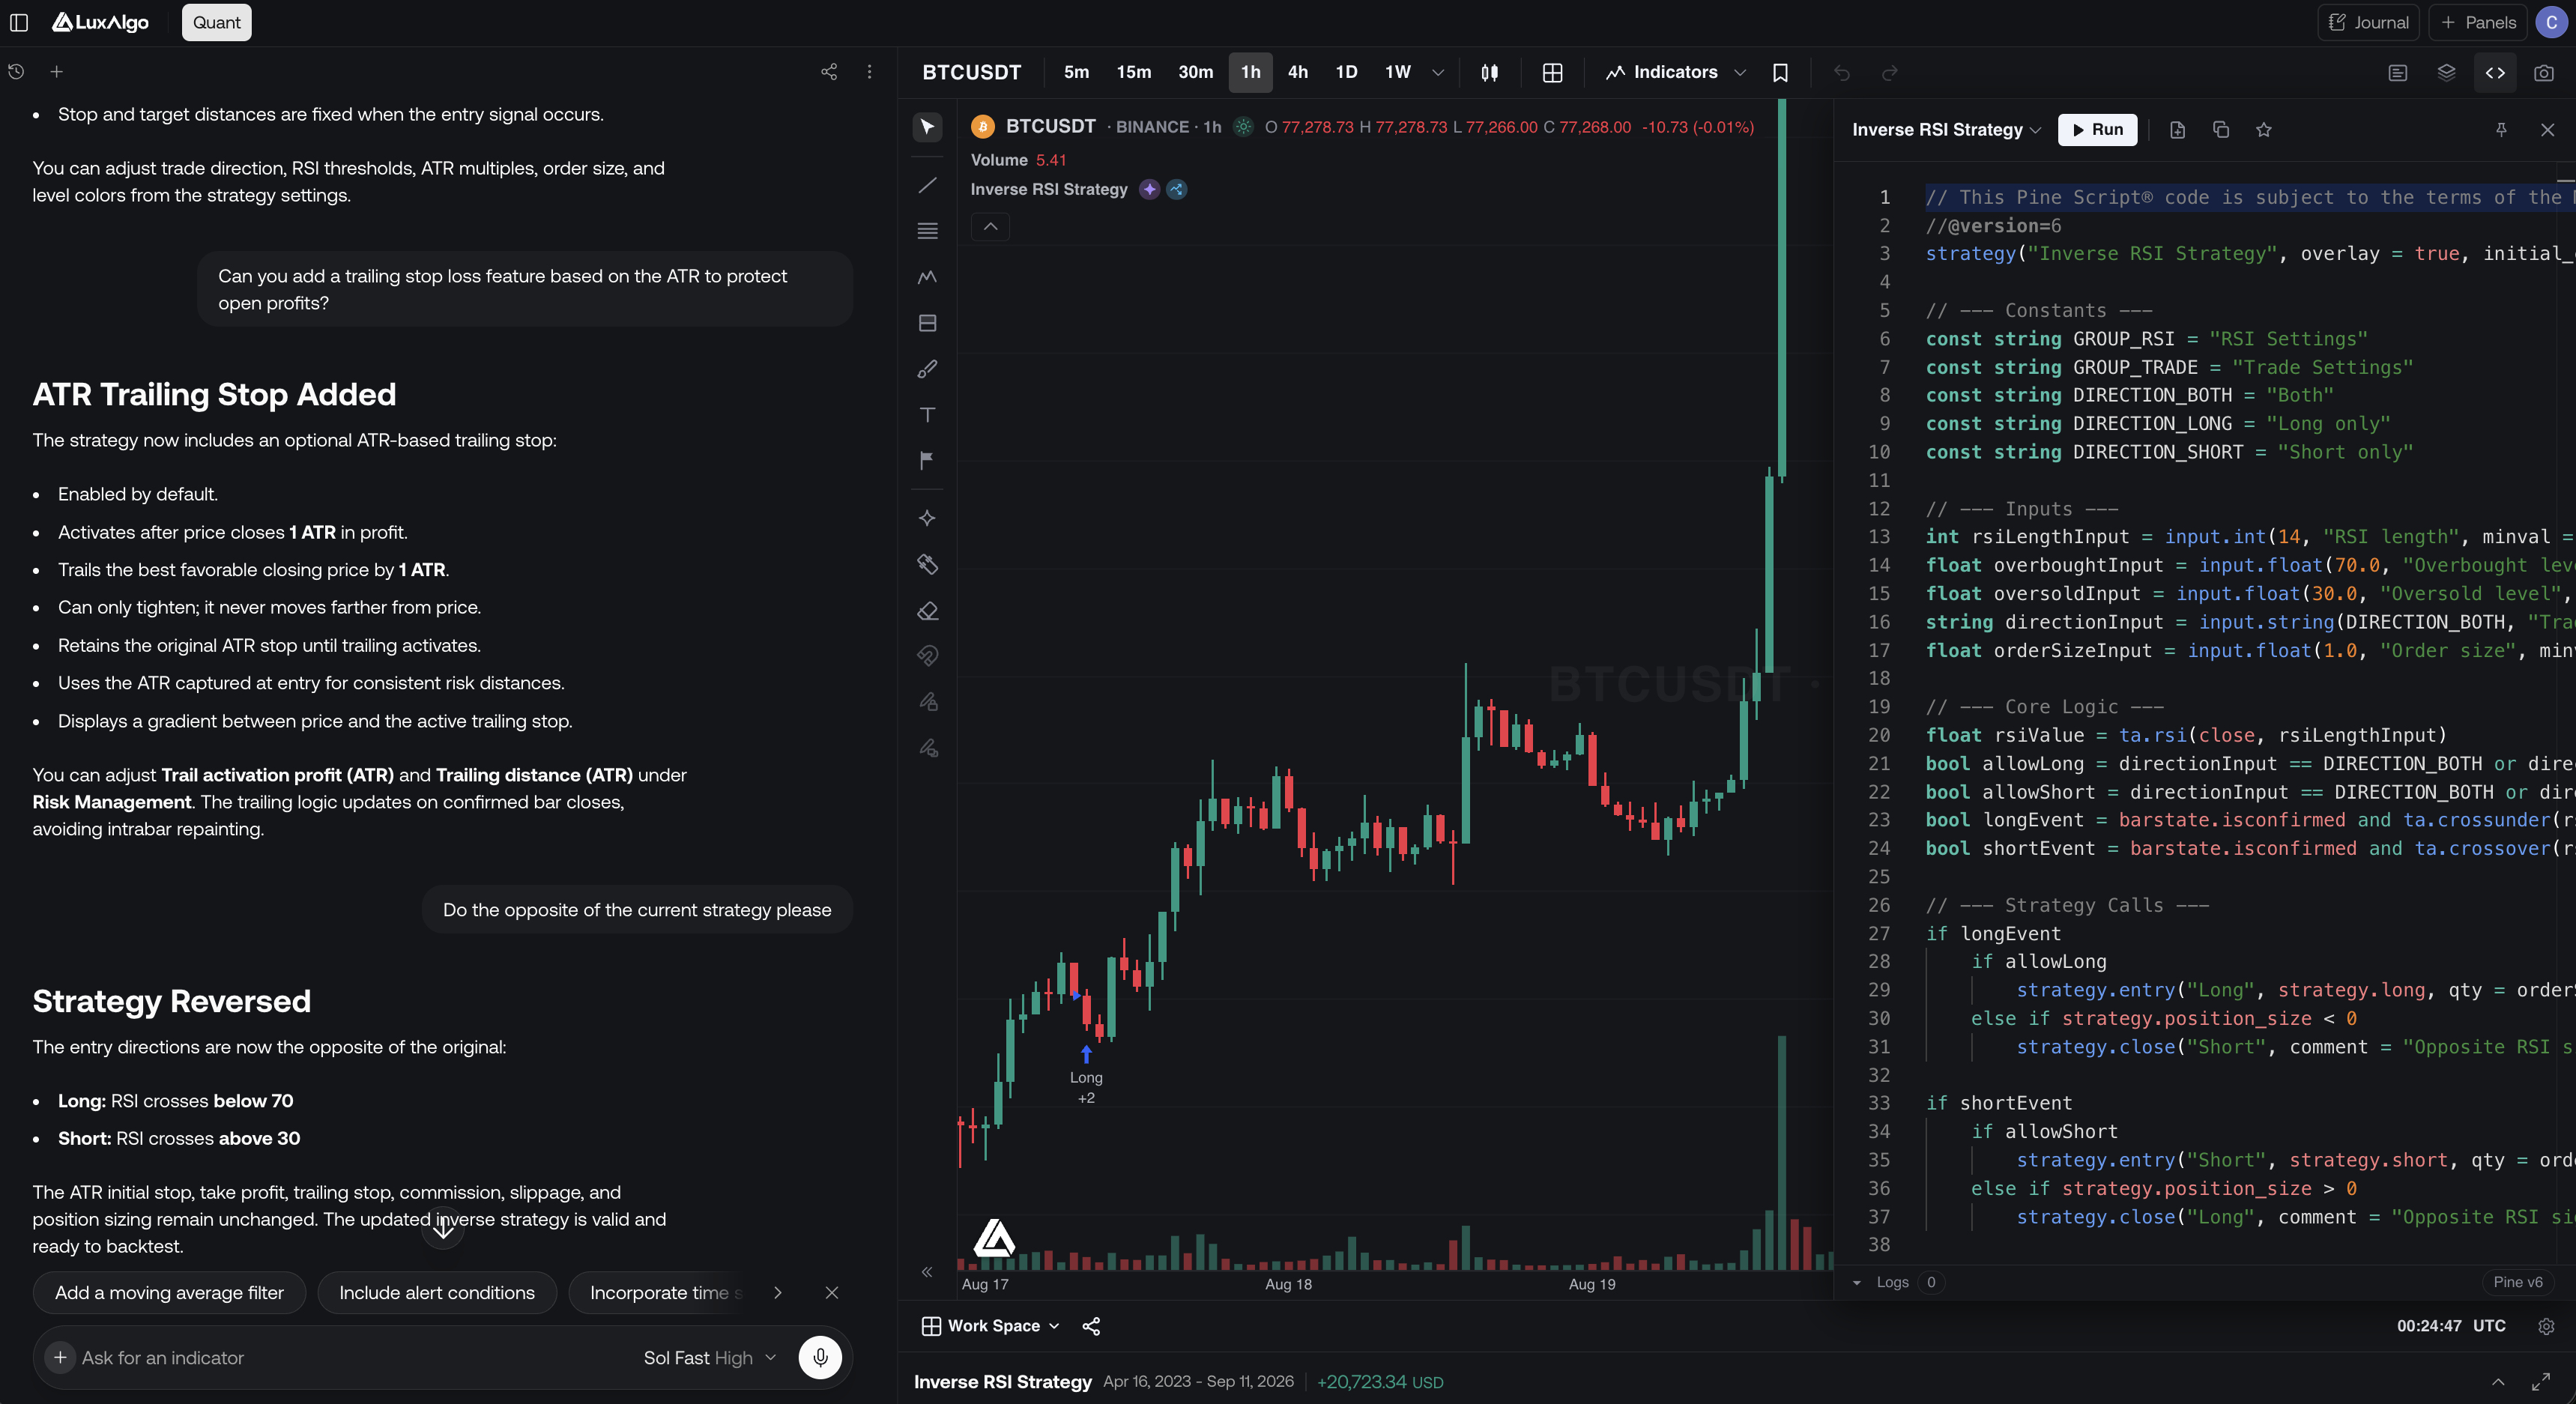
Put the chart on the symbol and timeframe you want to test, or include them in the request ("backtest this on 4h ETH"). Quant [sets the chart up](/platform/quant/working-the-chart#set-up-the-chart-from-a-prompt) before it writes the strategy.
Tell Quant the trade logic in your own words: what triggers an entry, what closes the position, and any risk rules (stop loss, take profit). The more concrete the conditions ("enter long when the 20 EMA crosses above the 50 EMA" rather than "buy on momentum"), the closer the first draft will be.
Quant writes the strategy and runs it on the chart's history. Open [**Pine editor**](/platform/charts/pine-editor) to review the script; you can edit it and **Run** it yourself (after you sign in).
Quant sees a one-line summary of the run (net P\&L, profit factor, trades, and max drawdown) and mentions it in the reply. The chart marks entries and exits, and a **Backtest Summary** strip appears below with net profit, trade count, win rate, max drawdown, and profit factor. How to read all of it (the summary strip, the full viewer, inputs, and saving runs) is covered in [Strategies](/platform/charts/strategies).
## Convert an indicator into a strategy [#convert-an-indicator-into-a-strategy]
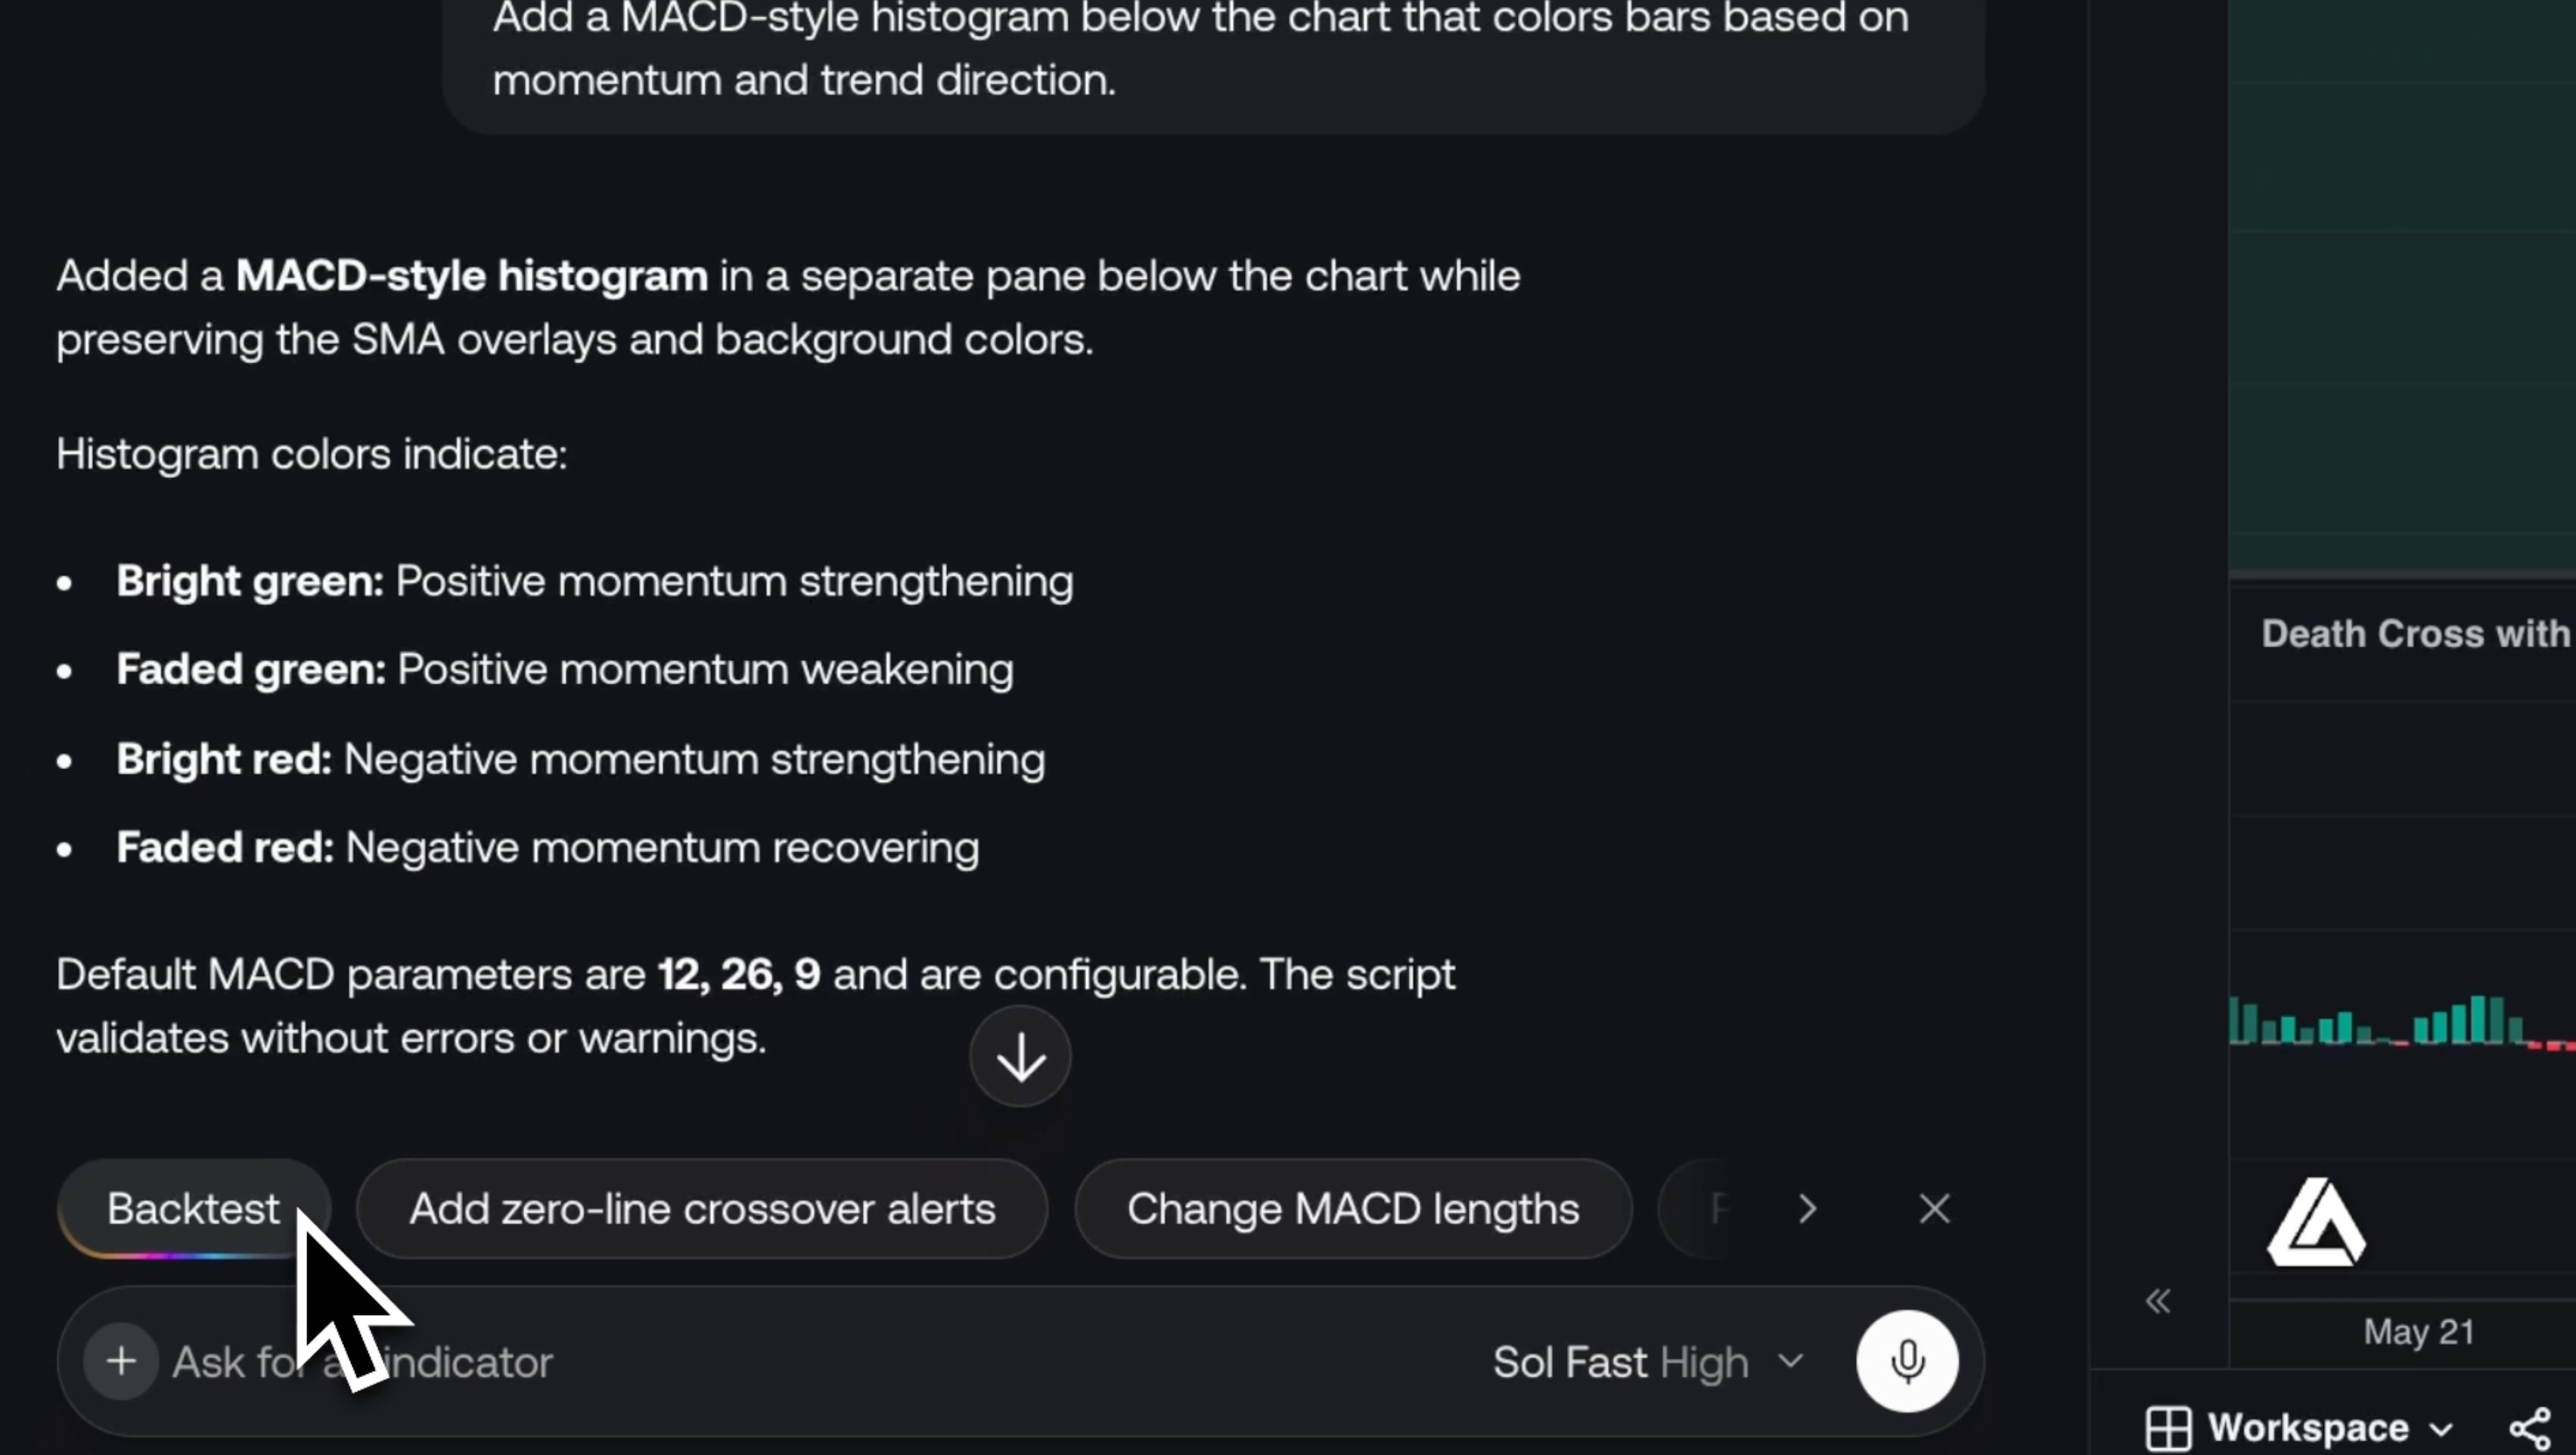
If the editor already holds an indicator, you have two routes:
* Click the **Backtest** button in the toolbar. Quant rewrites the script with entries and exits while keeping the original concept.
* Ask in the chat: "convert this into a strategy that goes long on the buy signals", which is useful when you want to control exactly how signals map to trades.
The toolbar **Backtest** action only appears when the editor holds indicator code (not already a strategy).
## Dig into the trades [#dig-into-the-trades]
Ask about specific trades and Quant reads them from the strategy itself: side, quantity, entry and exit time and price, and P\&L.
* "Where did the strategy enter last week, and what did those trades make?"
* "Which of the last 20 trades were the biggest losers?"
* "How long did the last five trades stay open?"
For the full picture, open the **Backtest Viewer** from the summary strip:
| Tab | What it shows |
| -------------------------------------------------------------- | ------------------------------------------------------------------------------------------- |
| [Performance](/platform/charts/strategies/performance) | The net profit curve, summary metrics, daily P\&L, weekday results, and longs versus shorts |
| [Trades Analysis](/platform/charts/strategies/trades-analysis) | Distributions: P\&L, win rate, and trade duration against P\&L |
| [Trades Log](/platform/charts/strategies/trades-log) | Every trade, sortable, with a calendar view of daily results |
| [Simulation](/platform/charts/strategies/simulation) | How the results vary when the trades repeat or arrive in a different order |
## Tune it without re-generating [#tune-it-without-re-generating]
To test a different value, ask Quant to change the input ("try a 50-period filter") instead of rewriting the strategy. The strategy re-runs and its backtest updates. See [Change a script's settings](/platform/quant/working-the-chart#change-a-scripts-settings-without-new-code).
You can also open the settings gear in the toolbar yourself:
* **Inputs**: the script's `input.*` parameters (lengths, thresholds, toggles). Changes re-run the backtest immediately.
* **Properties**: the simulation itself (initial capital, order size, pyramiding, commission, slippage, and margin). Set **commission** and **slippage** before trusting any result: leaving them at zero flatters every strategy. See [Script settings](/platform/charts/strategies#script-settings).
Use the chat when you want to change the *logic*; use inputs and properties when you want to change the *numbers*.
## Stress-test it with Simulation [#stress-test-it-with-simulation]
The **Simulation** tab in the Backtest Viewer replays the backtest's closed trades many times:
* **Resample** picks trades at random, with repeats, so totals vary. **Shuffle** keeps the same trades in a new order, so the path and drawdowns vary.
* Run **250**, **1,000**, or **2,500** simulations.
* Test a drawdown level as a multiple of the backtest's own max drawdown (**1.5×**, **2×**, **3×**, or your own), and see how often runs got that deep.
* **Risk of ruin** is how often a run lost all of the starting capital.
Simulation works from the trades the backtest produced, net of commission. Its numbers are estimates of repeatability and sequencing risk, not predictions, and it can't show market conditions the backtest never saw. The [Simulation guide](/platform/charts/strategies/simulation) walks through every setting and chart.
## Fix errors [#fix-errors]
Quant code repair is included with **Premium**, **Ultimate**, and **AI Ultra**. See [Plans](/platform/account/plans) for feature access.
**Fix with Quant** addresses syntax and runtime errors. Runtime errors are the ones to watch with strategies: they surface only after the script runs over history or hits new bars, and appear as a message at the bottom of the chart.
## Before you trust a result [#before-you-trust-a-result]
* **Use a standard chart type.** Heikin Ashi candles are averaged prices you can't trade at, so a backtest on them isn't realistic.
* **Check the sample.** A handful of trades is noise. Look at the trade count before the profit.
* **Re-run where you'll trade it.** Results depend on the [symbol, timeframe](/platform/charts/introduction), and data they ran on, and don't carry over to another market or interval.
To find strategies built from LuxAlgo toolkit conditions instead of writing your own, use [Strategy Screener](/platform/ai-backtesting/introduction).